Operating Experience
First-hand knowledge of airlines, aircraft operations and fleet economics.
Our Strategies
Metolius Aviation Opportunity Group works with a number of partners to source, acquire and monetize commercial aviation engines and airframes.
Metolius Aviation Financial Advisory Partners structures financing for specialized aerospace and defense businesses — from supply-chain and inventory finance to private debt.
Metolius Aerospace Ventures arranges and invests in private companies focused on new technologies, fast-growing aerospace and defense businesses and companies generating significant cash flow.
01Metolius Aviation Opportunity Group
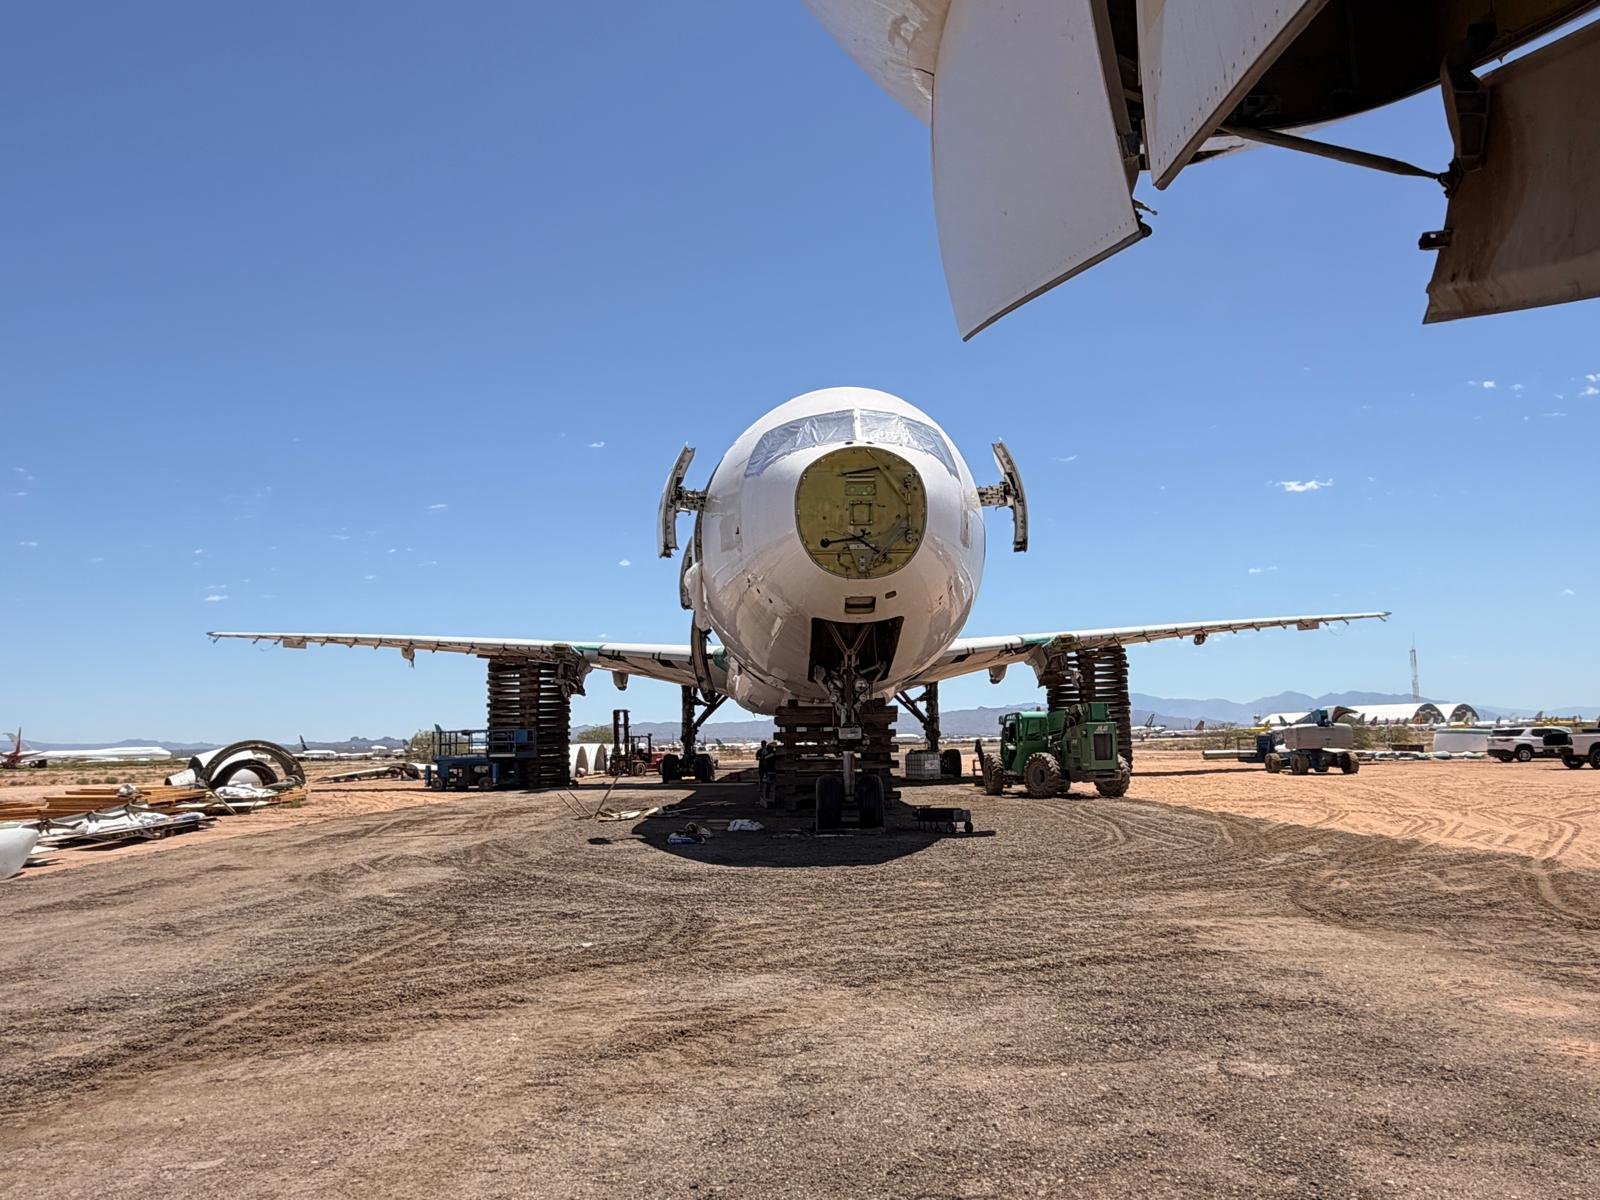
Aircraft delivery delays, engine availability issues and persistent aerospace supply-chain constraints are requiring airlines to operate existing fleets longer than originally anticipated — increasing demand for Used Serviceable Material (USM): certified components harvested from aircraft and engines that can be returned to service in the global fleet.
The Opportunity Group brings together experienced aviation operators, technical partners, financial partners and investors to acquire aircraft and engine assets at attractive values and monetize them through leasing, trading, teardown and the sale of components into the global USM market.
Current Focus — Boeing 777 Teardown
As of the latest publicly compiled 2026 fleet data, approximately 1,208 Boeing 777s are in commercial-airline fleets worldwide, operated by 74 passenger and cargo airlines. An additional 11 aircraft serve governments or military organizations, bringing the worldwide operational fleet roster to roughly 1,219 aircraft. This includes the 777-200, -200ER, -200LR, -300, -300ER and 777F.
For the Metolius teardown thesis, the most important figure is the 581-aircraft 777-300ER fleet. It is by far the largest passenger variant and represents nearly half of all commercially operated 777s, creating the broadest installed base for GE90-powered aircraft, replacement components and USM demand.
The transition is likely to be a long overlap rather than a rapid replacement. The 777X begins entering service in 2027, while the 777-300ER remains a major global fleet well into the late 2030s.
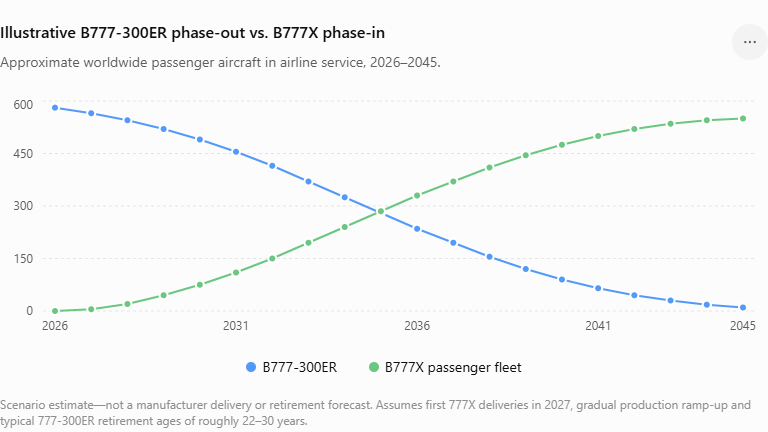
The principal takeaway for the Metolius teardown thesis is the likely 2030–2038 retirement window:
Conclusion High demand for USM over the next decade to support ageing B777-300ER fleets.
02Metolius Aviation Financial Advisory Partners
Financial Advisory Partners arranges and structures financing for aerospace and defense companies where understanding the equipment, the operators and the industry cycle matters as much as the balance sheet.
Our work spans supply-chain and inventory financing, receivables factoring and private debt — solutions designed around the cash-flow realities of manufacturing, MRO and technology businesses.
Transaction
MAC arranged financing for German aircraft manufacturer Grob Aircraft. The financing supported the business through to its subsequent acquisition by defense technology company Helsing.
grobaircraft.com03Metolius Aerospace Ventures
Metolius Aerospace Ventures arranges and invests in private companies, focused on new technologies, fast-growing aerospace and defense companies and companies generating significant cash flow.
We believe investment strategies in aerospace and defense are evolving rapidly in the current global environment, and we work with debt and equity partners to scale the industry’s growth in Europe and the USA.
Portfolio Partnership
MAC is a partner in Turbine Capital Group, a growing aviation services business focused on the acquisition and leasing of commercial aircraft engine stands — infrastructure supporting the global commercial engine market.
Visit turbinecapitalgroup.comFoundation
First-hand knowledge of airlines, aircraft operations and fleet economics.
Decades of experience acquiring, selling, leasing and managing commercial aircraft and engines.
Structuring aviation and aerospace financings — from individual asset transactions to institutional financings of approximately $500 million.
Long-standing relationships across airlines, lessors, banks, MROs, aerospace companies, engine specialists and institutional capital providers.
All three strategies are built on long-standing relationships. If you are an investor, operator, founder or technical partner, we welcome an introduction.
Contact MAC